Grocers must treat risk coverage as an evolving business priority, expert says

The unexpected can happen at any time in the grocery business—from equipment failures to property damage, customer incidents and other risks that can impact operations. And as the grocery landscape continues to evolve, so too do the risks that retailers need to consider.
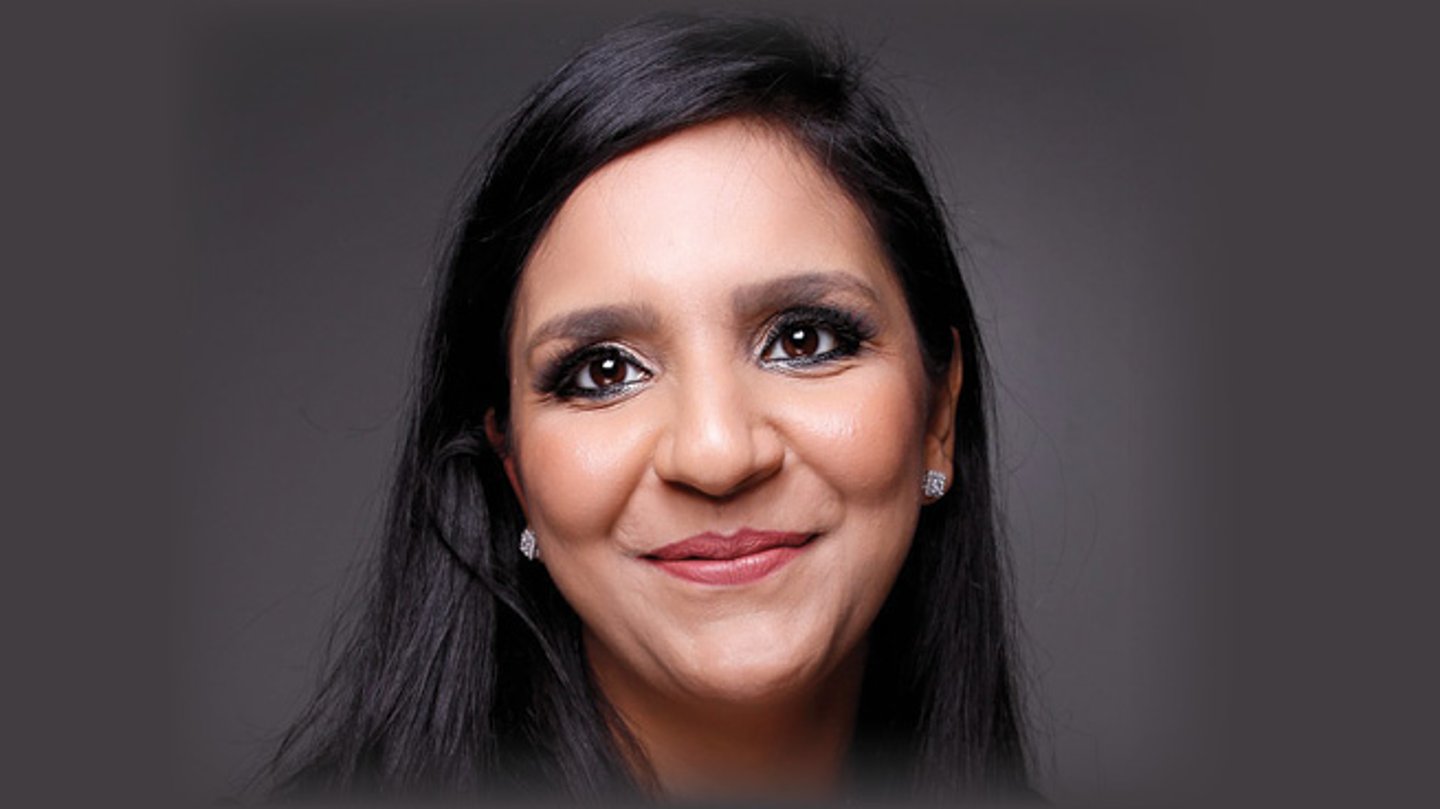
In this Q&A, Sidrah Khan, senior manager, small business insurance at TD Insurance, explores the changing needs of grocery retailers and how a proactive approach to insurance can help protect their business.
This interview has been edited for clarity and length.
How often should a grocer review and update their coverage, and what operational changes should trigger a policy update?
From a minimum perspective, of course, as per standard protocol, a grocer should review their coverage at least once a year. However, keep in mind that any major changes to your business should trigger a review sooner. When we’re talking about major changes—expanding your store, adding a bakery or deli, increasing inventory or investing in new equipment—we mean any major changes that can impact your risk profile as a business, as well as your insurer. One of the biggest mistakes we tend to see is ‘set it and forget it,’ which is risky because obviously your coverage should evolve as your business evolves. Grocery stores today look different than they did five, 10, 15 years ago with a lot of different operations. So, it’s important to make sure your insurance reflects how your business is operating.
What are the most common features or clauses grocery retailers overlook?
Most grocers are focused on protecting their building, their equipment, their inventory—they’re thinking about insurance to protect what they own. They don’t always consider the financial impact of having to close their doors for a few days or weeks at a time because of an insurable event. So, often we see businesses not thinking about business interruption, which can create exposure.
READ: Are you truly prepared for the unexpected?
Liability claims such as slip-and-falls are common in retail. How can store managers best document daily maintenance to protect the business against liability?
It’s critical that you are consistent. The most important thing before any kind of documentation is to make sure you have the proper risk processes in place to protect your grocery store. Assuming you have all safety checks in place, ensure you maintain detailed records—including inspection, cleaning and maintenance procedures. Documenting these steps demonstrates you are following proper protocols and taking all reasonable steps to maintain a safe environment.
All of this is important because if there is a liability claim, you have all your documentation to show you did everything you needed to do, and to help build your case as well. More broadly, think about liability risk as part of your overall business protection strategy. It’s not something you should be thinking about after an incident occurs. Think about it from the get-go so you can prevent such situations from happening.
How do specialized in-store operations—hot bars, delis, bakeries or butcher counters— change a grocery store’s liability profile?
Baking, cooking, cutting meat on site and other operations like that can introduce additional risks because now you’re not just a traditional grocery store, you’re also preparing, handling and serving food. Expanding your operations with such services can open you up to additional liability exposure, which is where your coverage needs to meet the needs of your business as it grows. For example, hot food spilling on a customer could be a liability issue, or there could be contamination concerns. And now that you’re producing food or baked goods on site, you take on greater responsibility for appropriate product labelling. So, it’s very important that you continue to have regular conversations with your insurance provider or licenced advisor to help ensure that your coverage is aligning with the realities of your business.
What is your advice for grocers wanting to move from a “set it and forget it” mindset with their insurance?
Constantly think about your budgeting, your cash flow, your financial plan and your business plan, and always think about insurance as part of that plan. Most resilient businesses will continuously look at their operations and their growth model, and try to ensure their insurance adapts as their business grows.
This article was first published in Canadian Grocer’s September/October 2026 issue.